Key Takeaways
- The best card for you should support spending you already do, not create reasons to spend more.
- Annual fees, interest rates, and repayment habits can matter more than a high reward rate.
- Reviewing a few months of expenses makes it easier to realistically compare card features.
- Different card types are designed for different goals, including building credit, earning rewards, or reducing interest costs.
- Always read the account terms, including fees, reward limits, promotional periods, and the regular purchase APR.
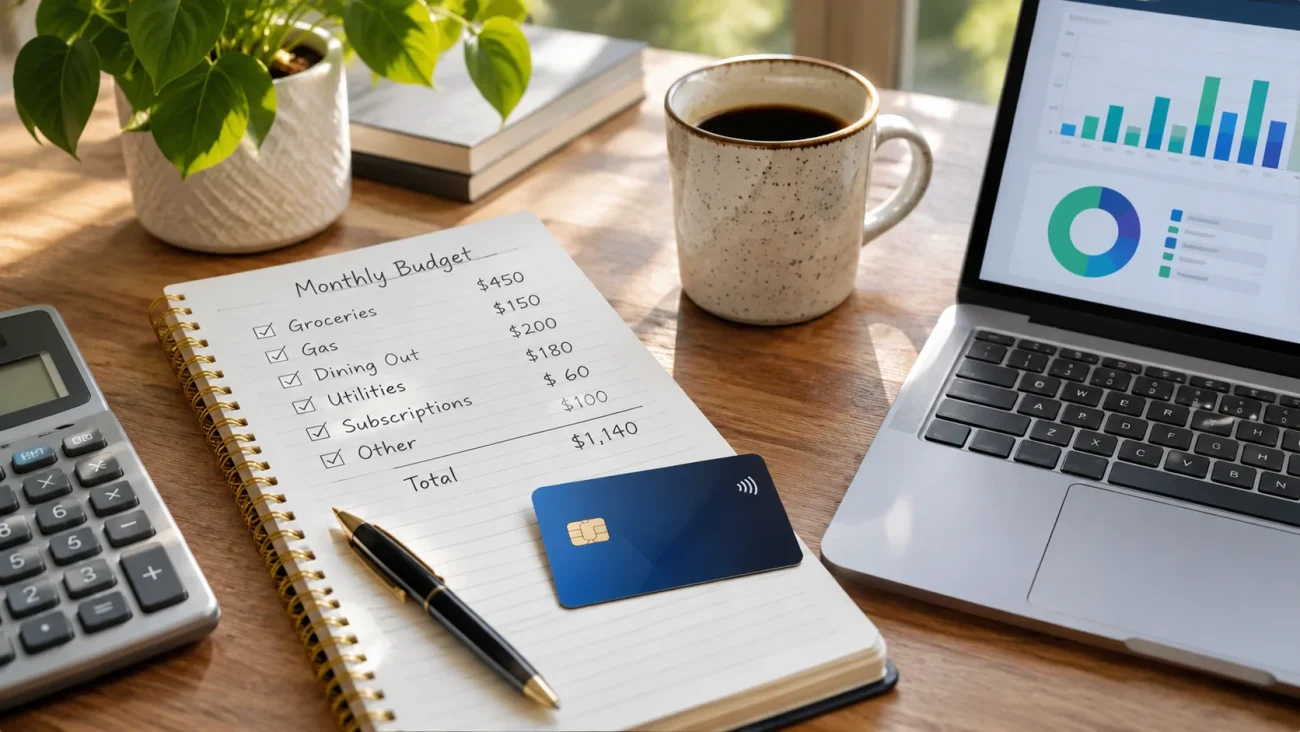
Choosing a credit card can feel complicated because offers often highlight rewards, welcome bonuses, or introductory rates. A better starting point is your own budget. Before comparing offers, identify how you normally spend, whether you pay balances in full, and what you want the account to help you accomplish. A card finder can also help narrow broad choices by asking about goals and spending preferences.
The right card is rarely the one with the flashiest promotion. It is the one whose costs, features, and payment requirements fit your everyday financial life. Rewards can be useful, but they lose much of their value if they lead to purchases you would not otherwise make or if interest charges accrue on unpaid balances.
Why Card Choice Should Start With Real Spending
A card may look appealing online but still be a poor fit for your routine. For example, someone who spends little on flights or hotels may get more practical value from simple cash back than from travel points with redemption rules. Likewise, a card with dining rewards may not be especially useful if most of your monthly purchases are groceries, fuel, utilities, or recurring services.
Start by looking for patterns rather than trying to change them. Your recent purchases can show which categories matter most, how much flexibility your budget has, and whether a reward structure is likely to be useful over time.
Step One: Review Three Months of Expenses
Use recent statements as a snapshot of normal spending. Three months is often enough to identify recurring costs without relying on a single unusual month. You can use a spreadsheet, a budgeting app, or a paper worksheet. The University of Virginia’s budgeting basics can offer additional ideas for organizing everyday financial decisions.
- Collect three recent bank account or credit card statements.
- Group purchases into broad categories, such as groceries, gas, dining, travel, bills, and shopping.
- Separate fixed expenses, such as rent or subscriptions, from flexible spending.
- Calculate an average monthly amount for each category.
- Mark costs that repeat and purchases that were one-time exceptions.
Step Two: Identify Your Main Financial Goal
Choose one primary goal before comparing cards. A card can have several features, but prioritizing one need helps prevent a rewards offer from distracting you from a more important cost or credit concern.
- Build or rebuild credit: Focus on manageable terms, affordable fees, and a payment plan you can maintain.
- Earn rewards: Look for rewards on categories that match regular purchases.
- Reduce interest costs: Compare the purchase APR, balance transfer fees, and promotional terms carefully.
- Manage a large purchase: Review how long any introductory rate lasts and what rate applies afterward.
- Keep things simple: Consider a card with clear terms and rewards that are easy to track and redeem.
Step Three: Match the Card Type to the Goal
Cash Back and Travel Rewards Cards
Cash back cards may suit people with steady everyday expenses who want straightforward value. Check the reward categories, spending caps, exclusions, and redemption requirements. Travel rewards cards may make more sense for frequent travelers who can realistically use airline, hotel, or travel-related benefits. Compare the annual fee, redemption options, and restrictions before deciding that a travel card is worthwhile.
Low-Interest and Balance Transfer Cards
If you plan to carry a balance, a lower ongoing interest rate might be more helpful than extra rewards. A balance transfer card can be useful for paying off debt, but check the transfer fee, how long the special rate lasts, and the rate after the special rate ends. Special financing does not erase debt, so your repayment plan should be realistic from the start.
Credit-Building Cards
People with limited or damaged credit histories may want to compare cards designed for credit-building. Look at annual fees, security deposit requirements when applicable, credit limits, and whether the account reports payment activity to major consumer reporting agencies. Approval is never guaranteed, so select options that align with your overall credit profile.
Step Four: Compare the Full Cost
Do not compare cards based only on a welcome offer or advertised reward rate. Review annual fees, purchase APR, balance transfer fees, cash advance fees, foreign transaction fees, late fees, reward caps, and expiration or redemption rules. Current offers can change, so reviewing current credit card rate data can help put interest costs into perspective.
A simple estimate can make the decision clearer:
Estimated yearly value = rewards earned + benefits used − annual fees − expected interest
Use your real spending averages in this calculation. Benefits you are unlikely to use should not be treated as savings, and expected interest can quickly outweigh modest rewards.
Step Five: Consider Repayment Habits
Your payment behavior should influence which features matter most. If you pay in full each month, rewards and convenience may deserve more weight. If you carry a balance, a lower rate and fewer fees may be more important. If you sometimes miss due dates, set payment reminders and review late-payment terms before applying. Available credit is not extra income, and rewards rarely offset repeated interest charges.
Step Six: Check Credit Readiness Before Applying
Before submitting an application, review your credit score or general credit range, payment history, existing balances, credit utilization, recent applications, income, and monthly obligations. Avoid applying for several cards at once simply to see what happens. Instead, narrow the list to two or three realistic choices and read each application disclosure carefully.
How to Compare Two Cards Side by Side
Create a short worksheet for each option. Include your primary goal, best spending categories, annual fee, regular APR, introductory APR period, reward rate, reward limits, redemption choices, foreign transaction fee, and estimated yearly value. Comparing only a few realistic options can make important differences easier to spot.
Common Mistakes to Avoid
- Choosing a card solely because of a large welcome offer.
- Ignoring the regular APR after an introductory period ends.
- Paying an annual fee for benefits that go unused.
- Changing normal spending habits just to chase rewards.
- Overlooking reward caps, exclusions, or redemption restrictions.
- Applying without considering credit readiness.
- Opening more accounts than you can comfortably manage.
Conclusion
The best credit card is not always the one with the most advertised perks. It is the one that fits your budget, usual spending, payment plan, and credit goals. By reviewing recent expenses and comparing all the terms, you can make a clearer long-term choice and see rewards as a bonus rather than a reason to spend more.
